

Wise: International Transfers
by Wise Payments Ltd.
4.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.8
- Price
- Free
- Download
- 50.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
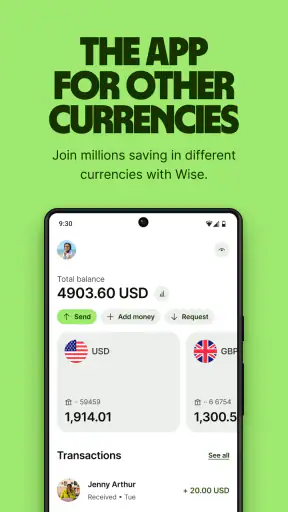
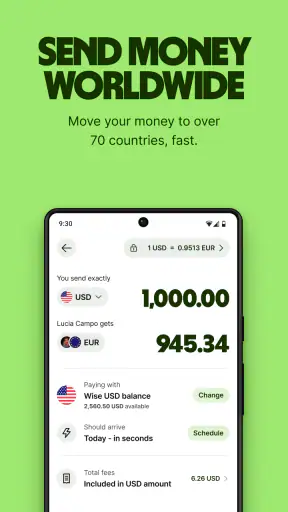
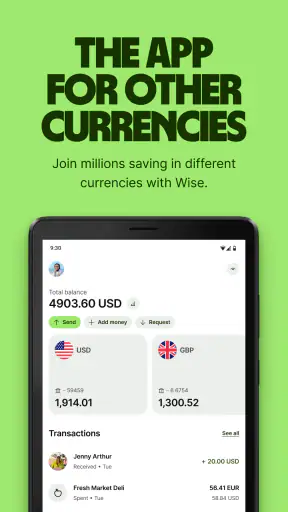
 Analysis by Getfullapps
I tend to judge finance apps by what happens after the first transfer: whether the process still feels understandable, whether the information is easy to check, and whether the app fits the way I actually move money. Wise: International Transfers is built for people who send, receive, or spend across borders, and in my experience its biggest strength is putting those activities into one focused place instead of making international money movement feel like a special banking chore.
It is a free finance app from Wise Payments Ltd., available for Everyone, and it has grown into a widely used service with over 50 million installs. Its average score is 4.8 from around 2 million ratings, which tells me that the basic experience works well for a large audience, although a high score should never replace checking whether the service matches your own country, currency, and payment habits.
How I decide whether Wise is the right money app
The first question is not simply whether I need to send money abroad. I ask how often I do it, whether I need to receive money in another currency, and whether I want an account that is centered on international use rather than everyday domestic banking. Those distinctions matter because the best choice for a person who sends occasional family support may be different from the best choice for someone paid by overseas clients every month.
I also look at clarity. Before confirming a transfer, I want to understand the amount I am sending, the currency the recipient should receive, the expected arrival information shown in the app, and the total effect on my balance. Wise is appealing here because its purpose is narrow and recognizable: it is designed around moving money between currencies, spending internationally, and handling incoming funds from abroad.
That focus makes it easier to compare with the usual alternatives. A traditional bank may already be the place where I keep my salary and pay bills, while a remittance service may be optimized for sending money to a particular country or recipient. A digital wallet may be convenient for online purchases, but not necessarily ideal for managing several currencies. Wise sits between these categories, with a stronger international identity than a standard current-account app and a broader everyday role than a one-purpose transfer counter.
My final decision also depends on the destination and the payment route. International transfers are not a single identical product: the recipient’s country, the currencies involved, the funding method, and local banking arrangements can all affect the experience. I would therefore use Wise as a practical tool, but I would still read the final transfer screen carefully instead of assuming every route behaves the same way.
The setup feels aimed at real cross-border routines
When I use an app like this, I want to get beyond a one-off transfer. The useful question is whether it can become part of a repeatable routine: receive money from an overseas customer, keep funds in a currency for a while, convert only when needed, or spend while traveling without opening a separate service for every step.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
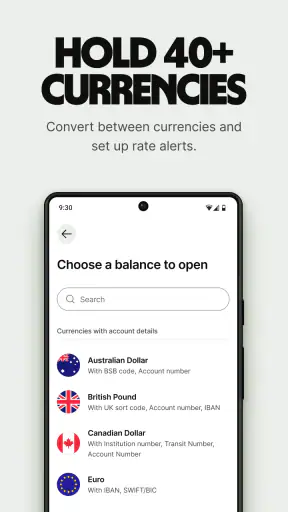
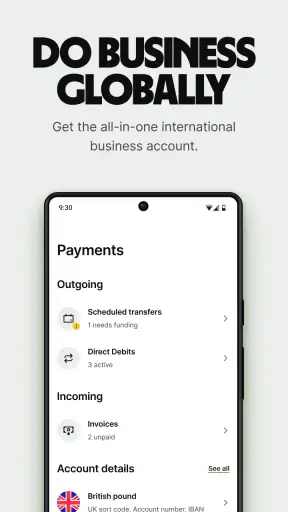
That is where Wise makes sense to me. Its store summary, “Send, receive, spend worldwide,” describes a wider workflow than simply pressing a send button. I can think about the app as a central place for international money decisions: money coming in, money going out, and money being used while I am away from home.
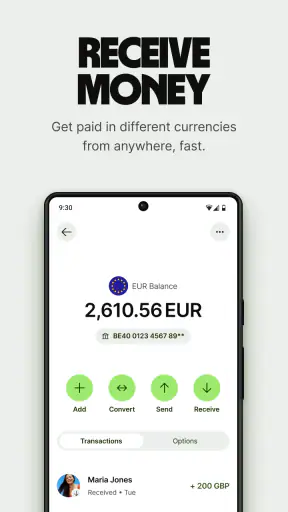
A practical example would be a freelancer who receives payment from a client in another country. Instead of treating every incoming payment as an emergency conversion, the freelancer can use the app to organize the money first and decide when it makes sense to move it onward or convert it. That does not remove the need to check fees and exchange details, but it can make the process less scattered than juggling email instructions, a bank portal, and a separate conversion service.
Why the international focus is its strongest advantage
The clearest win is concentration. I do not have to think of international transfers, receiving foreign funds, and spending during travel as completely unrelated tasks. For a person who crosses borders regularly, that can be more useful than a domestic banking app that technically supports international payments but treats them as an occasional add-on.
I also like the possibility of separating the decision to receive money from the decision to convert it. That is a subtle but important habit. If I convert automatically every time funds arrive, I lose control over timing and budgeting. If I can review the incoming amount first, I can decide whether I need the money in my everyday currency immediately or whether keeping it available for a later international expense is more sensible.
Another useful workflow is preparing before a trip rather than reacting at the airport or hotel. I would open the app in advance, check the relevant balances, and make sure I understand how I plan to pay. This reduces the chance of making a rushed decision on a poor connection or while dealing with unfamiliar local prices. Wise is particularly suitable for travelers who want one finance app built around international movement rather than a collection of disconnected travel tools.
Small habits that make the app more useful
My first tip is to treat the confirmation screen as a decision point, not a formality. I would check the sending currency, receiving currency, recipient details, and the final amount before approving anything. This is especially important when a name or account detail is copied from a message, because an app can make the transfer process smooth without making a mistaken recipient easy to recover from.
Second, I would keep a simple record of why each transfer was made. The app can help move the money, but it does not replace my own budgeting system. Adding a note in my personal records—such as rent, family support, travel, or freelance income—makes later reconciliation much easier, particularly when several transfers use similar amounts.
Third, I would avoid converting money merely because a balance is available. The ability to hold or manage funds across currencies is most useful when it supports a plan. Converting in small, unplanned bursts can make it harder to understand the real cost of a purchase and can encourage me to chase exchange movements that I cannot reliably predict.
For recurring payments, I would also verify the recipient information every time a new arrangement begins, even if later transfers look familiar. A saved workflow is convenient, but international payments deserve a quick review because the currency and destination are part of the transaction itself, not just background settings.
Where the usual alternatives can be better
Wise is not automatically the best choice for every financial task. If nearly all my money activity is domestic, a traditional bank app may be more practical because it already connects directly to my salary, local bills, savings, and other accounts. Adding an international-focused app could create another balance to monitor without solving a real problem.
A specialist remittance service may also suit someone who sends money to the same recipient through a familiar route and values a very simple, repeatable experience. If my needs are limited to occasional transfers and I do not expect to spend or receive money internationally, a narrower service may feel less distracting.
For online shopping, a digital wallet can sometimes be more convenient because it is already integrated into checkout. Wise becomes more compelling when I need broader control over international money rather than only a quick payment button. These are different categories, so comparing them solely by brand familiarity would be misleading.
I would be cautious about choosing Wise as a replacement for every banking function. Its appeal is international flexibility, not the promise that one app should manage my entire financial life. Someone who needs extensive domestic banking features, branch support, complex borrowing products, or a tightly integrated household account may prefer to keep a conventional bank at the center and use Wise only for cross-border needs.
What can create friction in everyday use
The same flexibility that makes international finance useful can require more attention. Multiple currencies mean I need to know which balance I am spending from and whether a purchase is being funded in the way I expect. That is manageable, but it is not as effortless as using one domestic account where every transaction appears in a single familiar currency.
Transfers also depend on accurate information and the route being used. I would not promise a recipient that money will arrive at a particular moment until I have checked the details shown for that transfer. A finance app can present the process clearly, but it cannot make every country, bank, or payment path behave identically.
There is also a mental cost to having more control. Wise can help me make a deliberate choice about when to send or convert, but that means I must actually review those choices. If I want a service that hides most currency decisions and simply handles domestic spending, the extra international control may feel like work rather than a benefit.
Finally, I would not judge the app only by its attractive interface or strong public rating. A rating of 4.8 is encouraging, and around 19 thousand written reviews add useful social proof, but my own experience will depend on the transfer route I use and how carefully I enter details. The rating supports confidence in the general product; it does not guarantee that every individual transaction will feel identical.
Moving from another service without creating confusion
The cost of switching is mostly organizational rather than technical. Before relying on Wise, I would list the currencies I actually use, the people or businesses that pay me, and the subscriptions or regular transfers connected to my old service. This prevents the common mistake of opening a new app but leaving important payment instructions unchanged elsewhere.
I would begin with a small, non-urgent transfer if the situation allows. That gives me a chance to understand the confirmation flow, see how the recipient information is displayed, and learn where balances and transaction records appear. I would not use an experimental first transfer for rent, a deadline-sensitive invoice, or money that someone urgently needs.
For a travel setup, I would move only the amount I expect to use rather than treating the app as a reason to relocate all my money. That keeps the trial controlled and makes it easier to compare Wise with my existing bank card or wallet. If the experience fits, I can gradually make it part of my routine; if it does not, I have avoided a complicated reversal.
People receiving payments should update their payment instructions carefully and tell senders exactly which details to use. A transfer app is only as reliable as the information attached to the transfer. I would keep old and new arrangements clearly labeled during the changeover so that a client, employer, or family member does not accidentally send money to an account I no longer monitor.
Version, availability, and who should consider it
The current Android version is 9.38.0, and it supports Android 7.0 or later. That makes it accessible to people using older Android devices, although I would still keep the operating system and the app updated when possible because finance apps handle sensitive activity and need a stable environment.
The app is free to install, which lowers the barrier to testing it. That should not be confused with every transfer or currency action being cost-free; I would always inspect the transaction details presented before confirming. The useful comparison is not “free versus paid” in the abstract, but whether the complete cost and convenience fit the route I need.
I think it is a strong candidate for frequent travelers, remote workers, international students, people supporting family abroad, and freelancers who receive money from other countries. It is also worth considering for anyone who wants to make international spending a planned part of their finances instead of relying on whichever domestic card happens to be in their wallet.
I would skip it, or at least postpone switching, if I rarely deal with foreign currencies, already have an international setup that is clear and affordable, or mainly need domestic banking. I would also choose a different primary service if my most important requirement is a full traditional bank relationship rather than cross-border money management.
My recommendation after weighing the trade-offs
My recommendation is straightforward: try Wise if international transfers, receiving foreign money, or spending abroad are recurring parts of your life. Its focused design gives those activities a clearer home than many ordinary banking apps, and the ability to think about sending, receiving, and spending together is more valuable than the short store description suggests.
I would approach it as a specialist companion rather than an automatic replacement for my bank. I would test one low-pressure transfer, read each confirmation screen, keep my records organized, and compare the result with the alternative I already use. That approach lets the app prove its value in my own currency routes instead of relying only on its popularity.
After using it, I see the main trade-off clearly. Wise offers more international control and a more coherent cross-border workflow, but that control asks me to pay attention to currencies, recipients, and transaction details. For me, that is a fair exchange when money regularly crosses borders. For someone whose financial life is almost entirely local, the extra layer may not justify changing habits.
Overall, I would recommend Wise: International Transfers to readers who want a practical finance app for international routines and who are willing to review each transaction carefully. Wise Payments Ltd. has made the product broad enough to support sending, receiving, and spending worldwide, while keeping the central purpose easy to understand. Its best feature is not a flashy extra; it is the way it brings several cross-border decisions into one place.
With an Everyone age rating, a free entry point, and a current release that remains available for Android users on version 7.0 or later, it is easy to explore. My advice is to start with a specific need—a trip, an overseas payment, or a foreign-currency income stream—then judge whether the app makes that task clearer. If it does, Wise can become a genuinely useful part of an international money routine; if not, a domestic bank or narrower remittance option may be the more sensible choice.
Pros
- Transparent exchange rates with fees shown before confirming a transfer.
- Supports transfers to many countries and multiple currencies.
- Multi-currency account helps manage money while traveling abroad.
- Debit card and virtual card options are useful for international spending.
- Strong security features, including biometric login and transaction notifications.
Cons
- Fees can vary depending on currency, payment method, and transfer speed.
- Some transfers may require identity checks or additional documentation.
- Cash deposits and certain local payment methods are not supported.
- Availability of cards and account features depends on the user's country.
- Customer support response times may be slow during complex account issues.
FAQs for Wise: International Transfers
What is Wise: International Transfers used for?
Wise is a financial app designed for sending money internationally, receiving payments, holding multiple currencies, and converting funds. After setting up an account, users can check exchange rates, estimate transfer costs, and send money to supported bank accounts. It is especially useful for travelers, expatriates, freelancers, and people who regularly deal with payments across different countries.
Are Wise transfer fees and exchange rates transparent?
Wise generally shows the transfer fee, estimated delivery time, exchange rate, and the amount the recipient should receive before you confirm a transaction. The total cost can vary depending on the currencies, payment method, transfer speed, and destination country. It is still worth reviewing the final summary carefully, because fees and available options may differ from one transfer to another.
Is Wise safe to use for international money transfers?
Wise uses account security measures such as identity verification, encrypted connections, login protection, and transaction monitoring. However, no financial service is completely risk-free. You should download the app from an official store, use a strong and unique password, enable available security features, and never share verification codes. Wise may also temporarily review or restrict transactions for compliance reasons.
What documents are required to create and verify a Wise account?
Wise normally asks for personal information such as your name, address, date of birth, phone number, and email address. Depending on your country, account activity, transfer amount, or regulatory requirements, you may also need to provide an identity document, proof of address, or additional information about the purpose of a transfer. Verification requirements can vary between users.
How long do Wise transfers take, and can they be canceled?
Transfer times depend on the currencies involved, the recipient’s bank, weekends and public holidays, payment method, and whether additional verification is required. The app usually provides an estimated arrival date before confirmation, but this is not always guaranteed. Cancellation may be possible while a transfer is still processing, although completed transactions generally cannot be reversed automatically.
Read About Wise: International Transfers in Your Language

Wise: International Transfers
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@wise.com, visit https://wise.com, or review their https://wise.com/privacy-policy.










